The week in brief
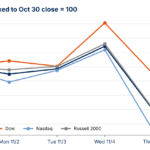
U.S. stocks ended the week lower after a volatile stretch. The S&P 500 fell 2.68% to 7,376.86, the Nasdaq Composite fell 3.37% to 24,579.42, the Dow fell 0.94% to 51,285.73 and the Russell 2000 fell 2.05% to 2,754.11. The Dow jumped 1,569 points on Wednesday, then dropped more than 1,800 points on Thursday as the S&P 500 fell 4.36% and the Nasdaq fell 5.52%; the PHLX Semiconductor Index fell 12.25% that day. Friday brought a partial rebound in the Nasdaq (+1.09%) and S&P 500 (+0.31%), while the Dow slipped 0.46%. The VIX closed at 25.64, up about 32% on the week. October payrolls rose 165,000, well above the roughly 59,000–65,000 expected, and Brent crude settled at $98.32 after its steepest weekly drop since 2020, per press reports.


Treasury yields
The 2-year Treasury yield fell 6 basis points during the week to close at 4.53%. The 10-year yield declined 7 basis points to 4.86%, and the 30-year yield dropped 5 basis points to 5.26%. Based on these closing yields, the spread between the 2-year and 10-year Treasury notes was approximately 33 basis points.
Key events
Monday, November 2: Stocks edged lower. The S&P 500 fell 0.51% to 7,541.40, the Nasdaq declined 1.07%, and the Dow gained 0.41%. Midterm elections were held Tuesday.
Tuesday, November 3: The S&P 500 rose 0.36% to 7,568.92, and the Nasdaq gained 0.83%. The Dow declined 0.38%. Press reports indicated that Democrats won both chambers of Congress.
Wednesday, November 4: Markets rallied broadly. The Dow gained 1,569.40 points, or 3.03%, to close at 53,356.12. The S&P 500 rose 1.58% to 7,688.62. According to press reports, Brent crude fell 9.73% to settle at $93.52.
Thursday, November 5: An AI-linked selloff sent the S&P 500 down 4.36%, the Nasdaq down 5.52%, and the Dow down 3.44%. Closing levels were derived from reported point changes; see the full report for calculation notes. The PHLX Semiconductor Index fell 12.25%. Reports cited investor concerns about data-center regulation, returns on AI investments, and borrowing costs.
Friday, November 6: The October jobs report exceeded forecasts. The Nasdaq gained 1.09%, the S&P 500 rose 0.31%, and the Russell 2000 advanced 0.89%. The Dow declined 0.46%. In Asia, the Nikkei fell 5.96%, and the Kospi dropped 6.02%. European indexes declined between 0.8% and 1.7%.
Economy and the Fed
October nonfarm payrolls increased by 165,000, compared with consensus estimates ranging from approximately 59,000 to 65,000 across press sources. September payroll growth was revised to 60,000. The unemployment rate declined to 4.1% from 4.2%.
Average hourly earnings increased 0.4% month over month and 3.1% year over year, compared with a consensus forecast of 2.9% annual growth.
The University of Michigan’s preliminary November consumer sentiment reading was 51.0, above the expected 48.0. One-year inflation expectations declined to 4.3% from 4.7%, while five-year expectations eased to 3.4% from 3.5%.
The Federal Reserve held the federal funds rate at 3.75%–4.00% on October
Darren Leavitt, Foundations Investment Advisors
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third-party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted.
Thursday’s closes are derived from AP point changes; see the full report for notes on derived and approximate figures.